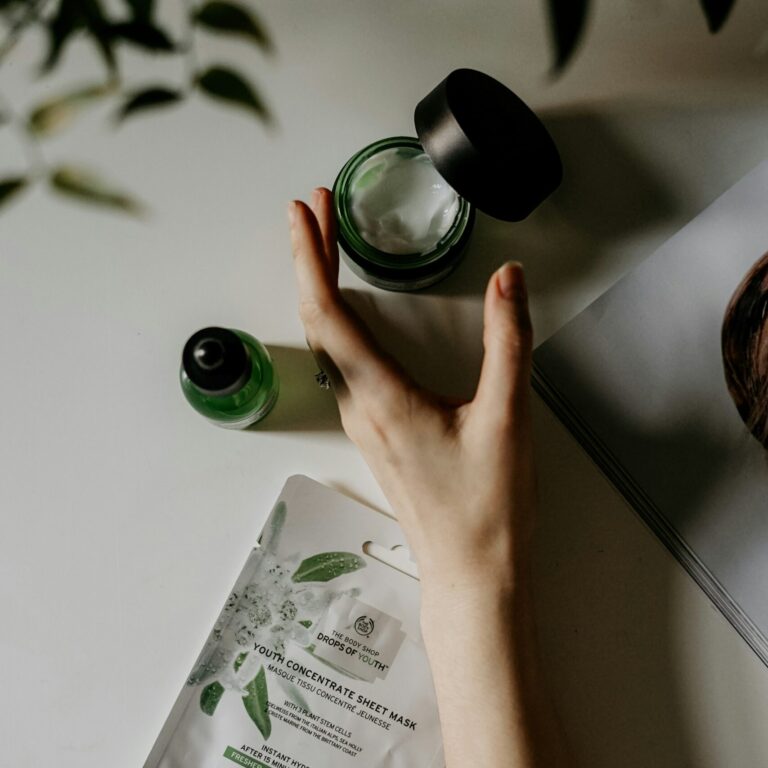
South Korea keeps turning up as the manufacturing engine behind the world’s biggest booms. Take semiconductors: Samsung Electronics and SK hynix supply the DRAM and high-bandwidth memory running the AI buildout, profiting from something much bigger than either company alone. Beauty is far less capital-intensive, but the same instinct is showing up in it. Manufacturing power sits underneath brands that span the globe and the viral sensations coming out of Korea’s own beauty market. Korean brokerages have been pricing this in for months; the rest of the world is still catching up.
K-Beauty’s rise is usually credited to K-pop and K-drama, and Kahi’s Wrinkle Bounce Multi Balm shows why: Kim Go-eun used it on-screen in The King: Eternal Monarch, and Korean searches for the “pink stick” spiked within days, and within a year, search volume for the balm had gone from roughly 100,000 to 12 million, with the brand selling more than 10 million units since. It kept turning up in dramas well past the one that made it famous. And The King wasn’t even a big hit, in comparison to the likes of Netflix’s Squid Games, Kpop Demon Hunters, The Glory, All of Us Are Dead, etc. Soft power explains why demand exists, not who captures the profit once it materializes.
That split turns on a basic distinction. Brands carry higher gross margins than manufacturers, but that margin comes with real exposure: marketing spend, retailer allowances, inventory risk. Manufacturers don’t have that exposure. Their return comes from formulating and producing for whoever is actually selling, not from picking which label is having its moment.
Three companies do most of the manufacturing behind that wave: Cosmax, Kolmar Korea, and Cosmecca Korea, original development manufacturers, or ODMs, whose combined client rosters span three distinct groups: the legacy majors, the Korean indie wave, and a third, far less visible tier.
The legacy majors get the most airtime, but that attention is disproportionate to their actual contribution. Cosmax’s relationship with L’Oréal, for instance, is cited constantly as proof of manufacturing quality, and it’s a legitimate signal, but just one account among Cosmax’s roughly 4,500 clients and its work with 18 of the world’s top 20 beauty companies. The headline value is real — legacy accounts lend credibility and stability — but in terms of what actually occupies the production lines and shows up in the numbers, this tier is the smallest of the three.
The indie wave, by contrast, is where the bulk of the business actually lives. These are brands outside the conglomerate structures of LG H&H, AmorePacific, and similar majors — labels without their own R&D or manufacturing, built instead on marketing and branding, relying entirely on ODMs to bring product to life. Beauty of Chosun, D’Alba, and most of today’s breakout Korean names emerged exactly this way, and Korean ODMs themselves point to this tier as the lion’s share of their revenue. The public imagination isn’t wrong to fixate here — social media has whipped the indie market into a genuine frenzy, and it’s expanding at breakneck speed. A quick factcheck on Amazon U.S. shows that 12 of the top 20 skincare brands purchased on the platform are Korean brands. Real upside, real competitive risk, and it’s the segment doing the most work for ODM revenue and operating income today.
The third bucket is the least discussed, but it may matter most for where growth comes from next. That same small group of ODMs formulates for dozens of clients at once, frequently running direct competitors through the same production lines, and most of that output belongs to established brands with no name recognition at all. This is the undiscovered pipeline — brands and products not yet part of the indie narrative but positioned to be the next wave of “hits” once they break through. Polaris’ tracking on Amazon and Ulta’s top facial-skincare SKUs, broken out by manufacturer rather than brand, sizes that bucket directly.
Speed is why brands choose that arrangement, and it’s less a preference than a necessity: K-beauty trends move fast, and a brand too slow to capitalize can lose the moment to whichever rival gets there first. Where large beauty companies can take 18 months or longer on novel formulations, Cosmax says it can move from concept to supply in as little as three. Kolmar Korea’s Packaged Product Service has cut that to three to six months, down from nine to 12. That gap decides whether a product reaches shelves while demand is still building or after it’s passed.
Sun care adds a further edge, since the U.S. FDA regulates sunscreen as an over-the-counter drug rather than a cosmetic, favoring established ODMs with existing compliant facilities over brands building that from scratch. Beauty of Joseon’s Relief Sun: Rice + Probiotics SPF50+ makes the point directly. It went viral on TikTok as a lightweight, no-white-cast sunscreen, but its UV filters were never on the FDA’s approved list, and the brand eventually pulled the original formula from U.S. shelves, now sold there only through K-beauty import retailers. Other Korean brands have fared better working through ODMs already formulating within approved filters, access built product by product, not assumed from popularity at home.
This whole investment case hinges on the durability of demand, and that’s exactly what broke last time. K-beauty’s last boom leaned on Chinese duty-free traffic that evaporated once the THAAD missile dispute hit in 2016–17, concentrated enough in China-heavy brands and channels to raise a fair question about whether this cycle rests on sturdier ground.
I think it does, and the reason is geography and channel. K-beauty demand has spread well beyond South Korea and China, into markets that barely registered last cycle. Polaris’ own tracking shows South Korean brands emerging as a major competitive force in facial skincare across the United States and key European markets, including the United Kingdom, Germany, Spain, Italy, and France – with Korean brands increasingly prominent as Amazon bestsellers and in U.S. specialty retail shops like Ulta.
Distribution has broadened too: K-beauty products once confined to specialty e-commerce are now on shelves at Target, Ulta, and other mainstream US retailers, a foothold the category lacked during the last cycle’s China duty-free boom. The shift is visible on both ends of my recent trip to Seoul. The guest mix at the Four Seasons skewed heavily Western, many stocking up on K-beauty before their flights home, buying behavior that increasingly doesn’t require the flight, now that the same products sit on shelves back home at Target and Ulta.
That shift gained a concrete marker in August 2026, when Sephora partnered with CJ Olive Young, South Korea’s leading beauty retailer, to launch the Olive Young K-Beauty Edit. The launch brought 19 Olive Young-curated Korean beauty brands to more than 500 U.S. Sephora stores and Sephora.com, prestige placement this cycle has and the last one didn’t.
Demand is spreading; whether it’s converting into profit is a harder question, answered by what the three ODMs themselves reported in the second quarter of 2026. Cosmax posted record earnings and operating profits of $53 million (up 21% from prior year quarter), as its U.S. subsidiary turned its first-ever quarterly operating profit. Kolmar Korea and Cosmecca Korea both posted record revenue and profit, numbers worth pulling apart. Kolmar’s operating profit jumped 50.2% to roughly $78 million, its highest quarterly figure on record. Cosmecca’s climbed 39.3% to roughly $23 million, a record that beat analyst estimates by nearly 16%, with Korea-based revenue up 62.6% on surging export orders.
Capacity plans are similar in spirit, if not in scale: Cosmax intends to more than quadruple total production capacity by 2027, the most aggressive stance of the three. Cosmecca is more conservative, already at 70–80% utilization on a single shift, with room to add a shift before Ochang comes online in 2027.
Good operating numbers and guidance don’t automatically make for a good investment. The companies also have to be attractively priced; beauty ODMs look relatively cheap, offering a brief window of investment opportunity before analyst coverage catches up.
What would undermine this investment case? A version of the 2016 shock could return in a different shape. On the U.S. side, a shift in tariff policy could change the cost of South Korean-manufactured product. In Europe, it’s more a compliance cost than a demand one: three EU regulatory regimes tightened this year and landed hardest on brands that reached Europe through a third-party importer rather than their own entity.
Brand normalization is a separate risk, since K-beauty could lose its novelty faster than manufacturing relationships can adjust. Or success may invite its own risks, since rivals watching the same margins could overbuild capacity once the case becomes obvious to everyone. None of that shows up in the numbers yet, but it’s worth checking each quarter.
South Korean stock market volatility is also worth addressing. This July, the KOSPI had its worst month since 2008, driven by an AI-memory unwind hitting Samsung and SK hynix, not anything specific to beauty. A broad South Korean risk-off move doesn’t spare anyone on local exchanges (Cosmecca trades on the KOSDAQ, not the KOSPI), but the exposure isn’t equal. Earlier that same July, as semiconductor weakness first dragged the KOSPI lower, Kolmar Korea, Cosmax, and Cosmecca Korea shares actually rallied — real evidence that beauty’s drivers are distinct enough to matter. That’s part of the case for owning it: a second growth engine, not a hedge against South Korean equity risk.
South Korea’s manufacturing engine built Samsung Electronics and SK hynix into two of the most important companies in the world. Beauty won’t produce a Samsung — the economics are smaller, the moats narrower — but it doesn’t need to. It just needs good bones, and this one has them.
This blog was penned by Kenneth Kim, Assistant Portfolio Manager, in September 2026. Mr. Kim joined Polaris as an Analyst in June 2016; he was promoted to Senior Investment Analyst in January 2021 and became an LLC member in January 2022. In January 2025, Mr. Kim was named an Assistant Portfolio Manager, working in cooperation with the portfolio managers on the investment direction of Polaris’ global and international portfolios.
For more on South Korea markets and stocks, please read: South Korea: Resolving Political Turmoil in 2025 May Boost Market or The AI Hardware Stack: Follow The Bottlenecks, Not The Chips
IMPORTANT INFORMATION:
This material is intended for information purposes only, and does not constitute: (i) financial, economic, legal, investment, accounting, or tax advice, (ii) a recommendation or an offer or solicitation to purchase or sell any securities or (iii) a recommendation for any investment product or strategy mentioned herein. References to specific securities are for illustrative purposes only.
The views/opinions expressed by Assistant Portfolio Manager Kenneth Kim are as of the article’s publication dated (September 30, 2026), and are subject to change without notice. Views and opinions of Kenneth Kim expressed herein do not necessarily state or reflect those of Polaris Capital Management, and are not nor shall be used for advertising or product endorsement purposes.
Polaris owns shares of all named companies in italics (SK hynix, Samsung Electronics, Cosmecca Korea) mentioned in this article as of the date of publication, unless otherwise noted. Polaris has no obligation to provide updated information on the securities/instruments mentioned herein. Information, particularly facts and figures, are dated and in many cases outdated; Polaris does not undertake any obligation to update such information. This information is not intended to be complete or exhaustive and no representations or warranties, either express or implied, are made regarding the accuracy or completeness of the information contained herein. Reliance upon information in this material is at the sole discretion of the reader.
Polaris Capital is an investment adviser registered with the Securities and Exchange Commission. For more information about Polaris, please contact us at (617) 951-1365 or email Client Service.
This website uses necessary cookies to make our site work. A handful of non-essential cookies seek to enhance the browsing experience, analyze website traffic and improve site usage and functionality via analytics. By clicking “Accept“, you consent to accept these non-essential cookies; however, you can opt-out by clicking "Deny". See our cookie policy here.
Investors should be aware that criminals impersonate the personnel of financial firms. Polaris Capital has been made aware that unknown persons have been impersonating Polaris personnel through fraudulent communications and online “investment forums". Please note that Polaris Capital does not use WhatsApp to communicate with clients or prospects. If you are contacted by anyone claiming to represent Polaris, we encourage you to verify the legitimacy of the communication before responding by contacting our main office directly or reaching out to a trusted Polaris contact with whom you have previously communicated.
DISCLAIMER: You are about to leave the Polaris Capital Management, LLC website and will be taken to the PCM Global Funds ICAV website. By accepting, you are consenting to being directed to the PCM Global Funds ICAV website for non-U.S. investors only.
IMPORTANT INFO: RETIREMENT CALCULATOR
The retirement calculator is a model or tool intended for informational and educational purposes only, and does not constitute professional, financial or investment advice. This model may be helpful in formulating your future plans, but does not constitute a complete financial plan. We strongly recommend that you seek the advice of a financial services professional who has a fiduciary relationship with you before making any type of investment or significant financial decision. We, at Polaris Capital, do not serve in this role for you. We also encourage you to review your investment strategy periodically as your financial circumstances change.
This model is provided as a rough approximation of future financial performance that you may encounter in reaching your retirement goals. The results presented by this model are hypothetical and may not reflect the actual growth of your own investments. Polaris strives to keep its information and tools accurate and up-to-date.
The information presented is based on objective analysis, but may not be the same that you find at a particular financial institution, service provider or specific product’s site. Polaris Capital and its employees are not responsible for the consequences of any decisions or actions taken in reliance upon or as a result of the information provided by this tool. Polaris is not responsible for any human or mechanical errors or omissions. All content, calculations, estimates, and forecasts are presented without express or implied warranties, including, but not limited to, any implied warranties of merchantability and fitness for a particular purpose or otherwise.
Please confirm your agreement/understanding of this disclaimer.
DISCLAIMER: You are about to leave the Polaris Capital Management, LLC website and will be taken to the PCM Global Funds ICAV website. By accepting, you are consenting to being directed to the PCM Global Funds ICAV website for non-U.S. investors only.