Indonesia’s benchmark stock index, the Jakarta Composite, fell 11.6% on October 16, its worst day since 1998, after MSCI proposed reclassifying the country from emerging to “standalone” status, skipping frontier. A final decision is due by June 30, 2027. If MSCI follows through, Indonesian stocks would leave its emerging-market indexes, and the passive funds that track them would be forced to sell, whether or not the underlying businesses have changed. That is the pitfall of indexing: a verdict on a whole market gets applied to every company in it, including the good ones.
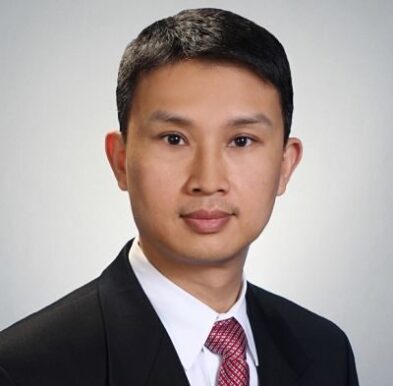
Here is a quick sit-down with Bin Xiao, Polaris portfolio manager, on what he thinks is and isn’t broken in Indonesia and what the episode shows about active investing in emerging markets.
It puts pressure on the biggest, most liquid stocks, because that’s where the money has to come out. Foreign investors have already net sold close to $5 billion this year – that’s investors choosing to sell. Index funds have no choice, and they only sell after MSCI’s final decision and an effective date, which isn’t set. Estimates run from about $3 billion to $5.6 billion, and most of it falls on the largest stocks left in MSCI’s main Indonesia index.
Some of that pressure is fair, because weak governance can raise the cost of capital for every company in a market, but prices can overshoot.
It’s a real step, but I wouldn’t assume it’s enough. The exchange and government rolled out reforms after MSCI’s January warning, and MSCI still wasn’t satisfied. Now it’s proposing a double downgrade, from emerging all the way to standalone, so even with the government cooperating, MSCI came back with something more severe. It points to opaque shareholding, suspected coordinated trading and weak enforcement, and the exchange is now going after concentrated ownership too.
You can see the government trying. The market rebounded more than 5% on October 20, though it’s still close to a six-year low. What matters now is whether they follow through. MSCI says it expects to proceed unless it sees clear evidence of material improvement during the consultation.
Start with the country. This downgrade has little to do with Indonesia’s growth story. You have close to 290 million people, an economy still early in its development, and natural resources, so there’s a lot of room to grow. You also have large, liquid companies that have long been a favorite play for investors. MSCI’s concerns apply to the whole market, but in my view the worst of it sits in tightly held conglomerates, and several of those, like Chandra Asri and Barito Renewables, are already out of its Indonesia index. I don’t think the large banks and the telecom are the target of the criticism, and I don’t see the downgrade changing their fundamentals. It would sweep them up anyway.
When I look at the growth, the quality and the valuation, these look like “the babies” to me. They fell more than the market because they’re the biggest, most liquid stocks, so they’re the easiest to sell. We own two of the banks, Bank Rakyat Indonesia and Bank Central Asia. At Bank Rakyat, the fundamentals are improving: in the first half, loans grew 16%, profit rose 17.5%, and funding and credit costs came down. Bank Central Asia is also growing, but more slowly. After the sell-off, both traded below their long-term averages.
MSCI is only part of it. The bigger issue, in my view, is fiscal policy: big new spending programs that widen the deficit. The market clearly doesn’t like that, and it’s a big reason the currency is weak and borrowing costs are up, along with higher oil prices.
I watch the currency first. A weaker rupiah and higher borrowing costs aren’t good for companies that depend on domestic consumption, like the banks and the telecom. Higher rates are more mixed. A bank with strong deposits can benefit, because it doesn’t have to pay up for its transaction deposits, and Bank Central Asia is strong there. The downside is weaker loan demand and more credit stress if rates stay high. These are real negatives, but in my view not big ones.
Then the budget and the central bank. Moody’s and Fitch both moved their Indonesia outlooks to negative this year. The new finance minister is a technocrat who says the budget has to stay credible- trimming here and there. The central bank governor’s surprise exit in July raised independence questions, so I want to see that it holds. To me it’s a sign the government is listening to the market and trying to adapt, but the proof is still to come.
If that proof doesn’t come, I’d trim. At the company level, I’d trim if credit costs rise faster than loans grow, and I’d sell if governance problems show up in the banks themselves.
This interview was conducted with Bin Xiao, CFA, Portfolio Manager, in October 2026. Mr. Xiao joined Polaris Capital Management, LLC as an Analyst in August 2006, and was promoted to Assistant Portfolio Manager in 2012. He became an LLC member in 2013. In January 2021, Mr. Xiao was promoted to Portfolio Manager. He is a generalist and performs fundamental analysis of potential investment opportunities. Mr. Xiao works closely with his fellow portfolio managers in all aspects of portfolio investment and strategy.
SOURCES
Based on Bin’s comments, Polaris compliance added the following source materials as backup for the facts and figures in this interview.
Market data through October 20, 2026.
IMPORTANT INFORMATION:
This material is intended for information purposes only, and does not constitute: (i) financial, economic, legal, investment, accounting, or tax advice, (ii) a recommendation or an offer or solicitation to purchase or sell any securities or (iii) a recommendation for any investment product or strategy mentioned herein. References to specific securities are for illustrative purposes only.
The views/opinions expressed by Portfolio Manager Bin Xiao are as of the article’s publication dated (October 28, 2026), and are subject to change without notice. Views and opinions of Bin Xio expressed herein do not necessarily state or reflect those of Polaris Capital Management, and are not nor shall be used for advertising or product endorsement purposes.
Information, particularly facts and figures, are dated and in many cases outdated; Polaris does not undertake any obligation to update such information. This information is not intended to be complete or exhaustive and no representations or warranties, either express or implied, are made regarding the accuracy or completeness of the information contained herein. Reliance upon information in this material is at the sole discretion of the reader.
The Jakarta Composite Index is the primary stock market benchmark of the Indonesia Stock Exchange (IDX). Indonesia is currently included in the MSCI Emerging Markets Index, representing approximately 0.46% of the benchmark (as of August 31, 2026). This is a a stock market index created by MSCI that tracks large- and mid-cap equity performance across developing nations. One cannot invest directly in an index.
Polaris Capital is an investment adviser registered with the Securities and Exchange Commission. For more information about Polaris, please contact us at (617) 951-1365 or email Client Service.
This website uses necessary cookies to make our site work. A handful of non-essential cookies seek to enhance the browsing experience, analyze website traffic and improve site usage and functionality via analytics. By clicking “Accept“, you consent to accept these non-essential cookies; however, you can opt-out by clicking "Deny". See our cookie policy here.
Investors should be aware that criminals impersonate the personnel of financial firms. Polaris Capital has been made aware that unknown persons have been impersonating Polaris personnel through fraudulent communications and online “investment forums". Please note that Polaris Capital does not use WhatsApp to communicate with clients or prospects. If you are contacted by anyone claiming to represent Polaris, we encourage you to verify the legitimacy of the communication before responding by contacting our main office directly or reaching out to a trusted Polaris contact with whom you have previously communicated.
DISCLAIMER: You are about to leave the Polaris Capital Management, LLC website and will be taken to the PCM Global Funds ICAV website. By accepting, you are consenting to being directed to the PCM Global Funds ICAV website for non-U.S. investors only.
IMPORTANT INFO: RETIREMENT CALCULATOR
The retirement calculator is a model or tool intended for informational and educational purposes only, and does not constitute professional, financial or investment advice. This model may be helpful in formulating your future plans, but does not constitute a complete financial plan. We strongly recommend that you seek the advice of a financial services professional who has a fiduciary relationship with you before making any type of investment or significant financial decision. We, at Polaris Capital, do not serve in this role for you. We also encourage you to review your investment strategy periodically as your financial circumstances change.
This model is provided as a rough approximation of future financial performance that you may encounter in reaching your retirement goals. The results presented by this model are hypothetical and may not reflect the actual growth of your own investments. Polaris strives to keep its information and tools accurate and up-to-date.
The information presented is based on objective analysis, but may not be the same that you find at a particular financial institution, service provider or specific product’s site. Polaris Capital and its employees are not responsible for the consequences of any decisions or actions taken in reliance upon or as a result of the information provided by this tool. Polaris is not responsible for any human or mechanical errors or omissions. All content, calculations, estimates, and forecasts are presented without express or implied warranties, including, but not limited to, any implied warranties of merchantability and fitness for a particular purpose or otherwise.
Please confirm your agreement/understanding of this disclaimer.
DISCLAIMER: You are about to leave the Polaris Capital Management, LLC website and will be taken to the PCM Global Funds ICAV website. By accepting, you are consenting to being directed to the PCM Global Funds ICAV website for non-U.S. investors only.